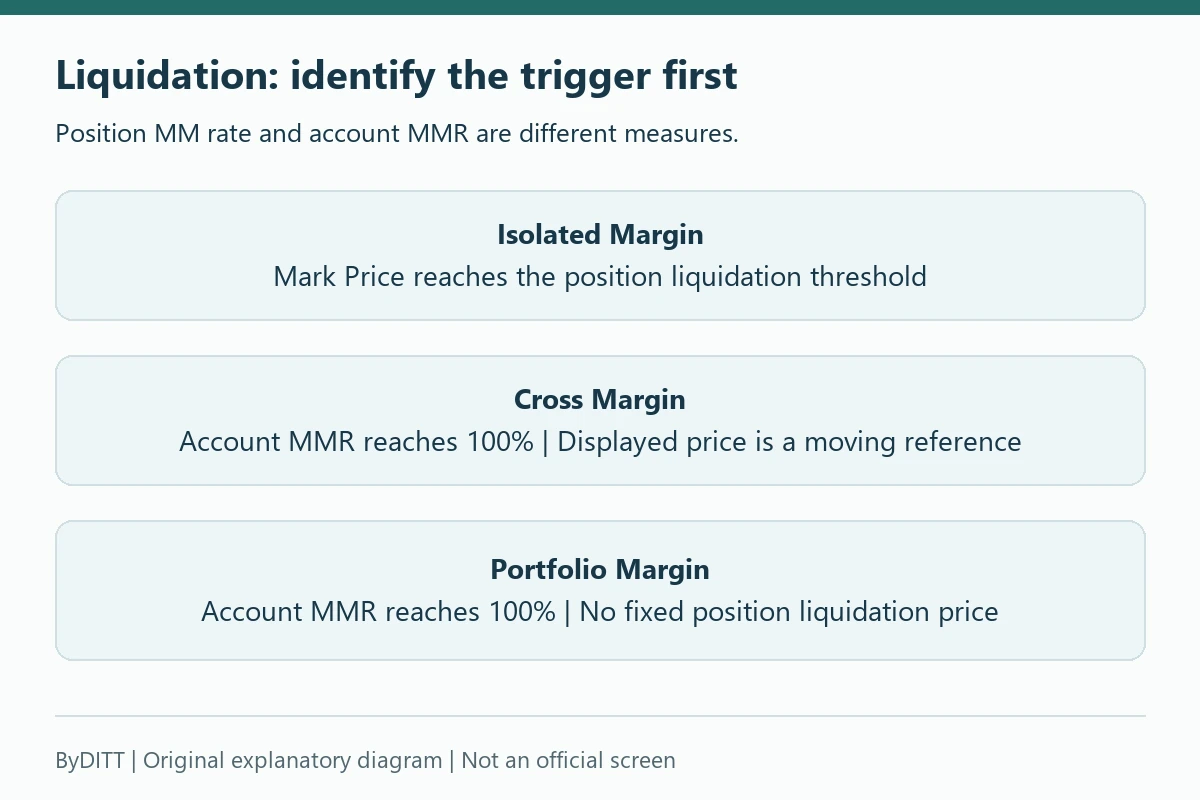
Bybit liquidation is triggered by risk thresholds, not by the candle you happen to be watching. In Isolated Margin, the Mark Price reaching the position’s liquidation price is the key trigger. In Cross and Portfolio Margin, account maintenance margin ratio (MMR) reaching 100% is decisive. A Cross Margin price is a moving reference; Portfolio Margin has no fixed position liquidation price. This guide explains what changes that risk and how to monitor it.
Reviewed on 19 October 2026. This guide explains liquidation triggers and record checks, not a strategy for a particular account. The current UTA liquidation rules: Isolated Margin were updated on 15 October 2026. Contract type, platform entity and the live account state take priority over a generic calculator.
What liquidation means on Bybit
Liquidation occurs when a position or account no longer satisfies the applicable maintenance margin requirement. The liquidation engine takes over risk management and attempts to reduce or close exposure under the current product rules. A liquidation price is not a recommended stop-loss level, and it is not a promise that your final loss will equal a simple chart calculation.
Bybit’s current order execution and liquidation FAQ distinguishes two trigger models:
- Isolated Margin: liquidation occurs when the Mark Price reaches the position’s liquidation price.
- Cross or Portfolio Margin: liquidation occurs when the account maintenance margin ratio reaches 100%; a displayed price is a dynamic reference.
Two percentages can have similar labels but different meanings. A contract maintenance margin rate, such as the hypothetical 0.5% used below, helps determine a position requirement. Account MMR is a ratio used to assess the account. Do not compare 0.5% directly with the 100% account liquidation trigger. Record the field name, margin mode and unit before interpreting a screenshot.
Mark Price, last traded price and index price
| Price | What it represents | Why it matters |
|---|---|---|
| Last Traded Price (LTP) | The most recent trade on Bybit | Common chart and order-execution reference; can differ from Mark Price |
| Mark Price | A fair-price reference derived from index and basis inputs | Used to trigger liquidation and for risk calculations under current derivatives rules |
| Index Price | A reference built from underlying market data | Contributes to Mark Price and may be available as a conditional-order trigger |
Bybit’s Mark Price documentation explains that liquidation uses Mark Price rather than the default LTP chart. The two can diverge. That is why a candle may appear not to touch the liquidation line even though the position is liquidated.
Why a stop loss may not prevent liquidation
A stop order has a trigger price and an execution price. If the stop is set to trigger on LTP while liquidation is triggered by Mark Price, the Mark Price can reach liquidation first. Even when a stop triggers first, it can execute with slippage or only partially fill in a fast or thin market.
- Check whether the stop uses Last, Mark or Index as its trigger.
- Leave a meaningful buffer between the stop trigger and the liquidation threshold.
- Size the position so ordinary slippage does not create an unacceptable loss.
- Confirm the order is active, reduce-only where appropriate and large enough to close the intended position.
- Do not treat TP/SL as a substitute for monitoring account MMR.
Diagnostic example, not a market replay: assume the long-position threshold in the calculation below is 45,226.13 USDT. At one instant, LTP is 45,500 USDT and an LTP stop is set at 45,300 USDT, but Mark Price is already 45,200 USDT. The stop has not met its LTP trigger while the liquidation condition can already be met. These deliberately hypothetical values show why comparing only the default candle with a stop line is incomplete.
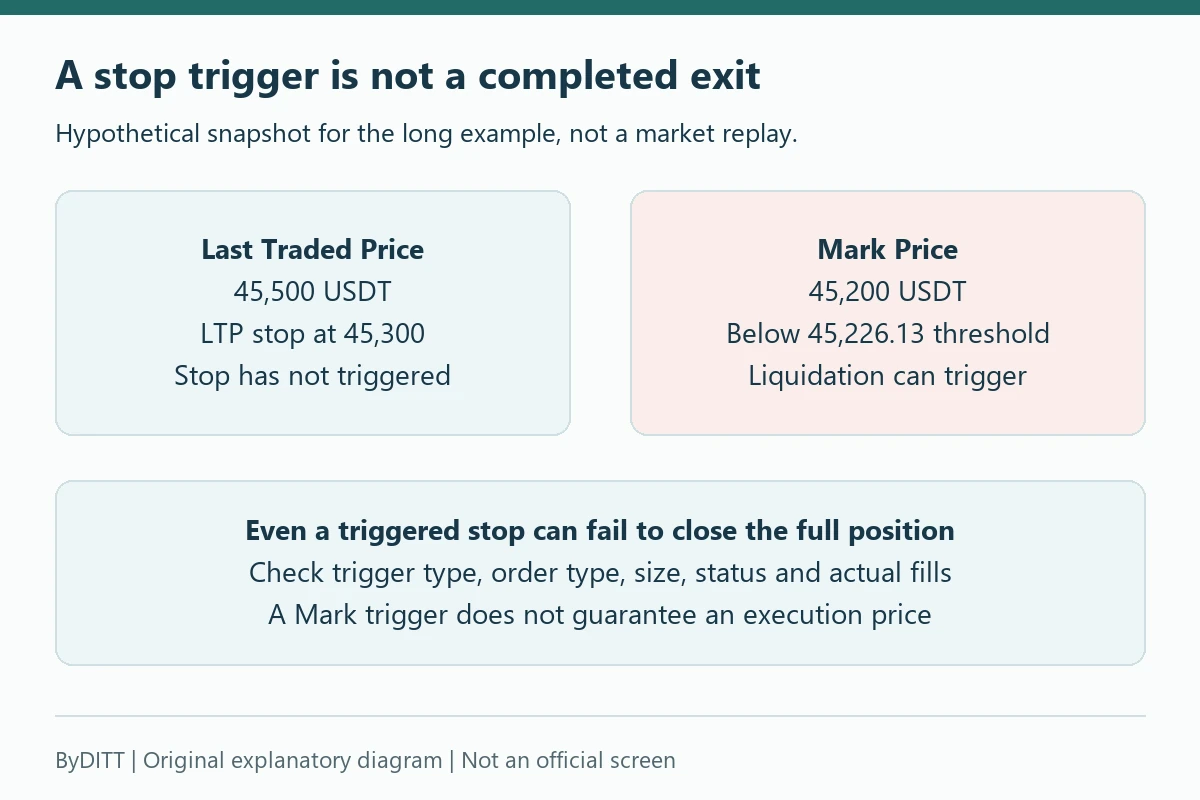
Separate “not triggered,” “triggered but unfilled,” and “partially filled.” A conditional limit can remain unfilled; a market exit can slip. Using Mark Price as the trigger does not turn the order into a guaranteed stop. For detailed order-status and price-protection diagnosis, use our stop-loss troubleshooting guide after confirming that its contract and order type match yours.
Isolated Margin: position-level risk
In Isolated Margin, margin is assigned to a specific position. Adding margin can move the liquidation price farther away by reducing effective leverage, while removing margin can bring it closer. The loss scope is more directly tied to the position, but fees, added margin and actual execution still matter.
- Check entry price, position size, assigned margin and maintenance margin rate.
- Use lower leverage to create more distance from liquidation.
- Adding margin increases capital at risk in that position.
- Auto-Margin Replenishment can draw from available balance if enabled; it does not make the trade safe.
- Partial position reductions can change the liquidation calculation and realized loss.
Worked example: a scoped Isolated Margin calculation
This independent arithmetic example uses the current Isolated Margin linear-contract formula in UTA liquidation rules: Isolated Margin. Assume one BTC, a 50,000 USDT entry, 10x leverage, a 0.5% maintenance margin rate, zero extra margin and zero maintenance margin deduction. Fees, funding, price rounding and later tier changes are excluded. The rates are assumptions, not a claim about today’s BTCUSDT tier or your fee rate.
With those restrictions, the long expression reduces to entry × (1 − 1 ÷ leverage) ÷ (1 − MM rate). The short expression uses entry × (1 + 1 ÷ leverage) ÷ (1 + MM rate). The fee-exclusive initial-margin component is 50,000 ÷ 10 = 5,000 USDT; this is not a recommended deposit amount.
| Illustrative case | Calculation | Result |
|---|---|---|
| Long, 10x | 50,000 × 0.90 ÷ 0.995 | 45,226.13 USDT |
| Short, 10x | 50,000 × 1.10 ÷ 1.005 | 54,726.37 USDT |
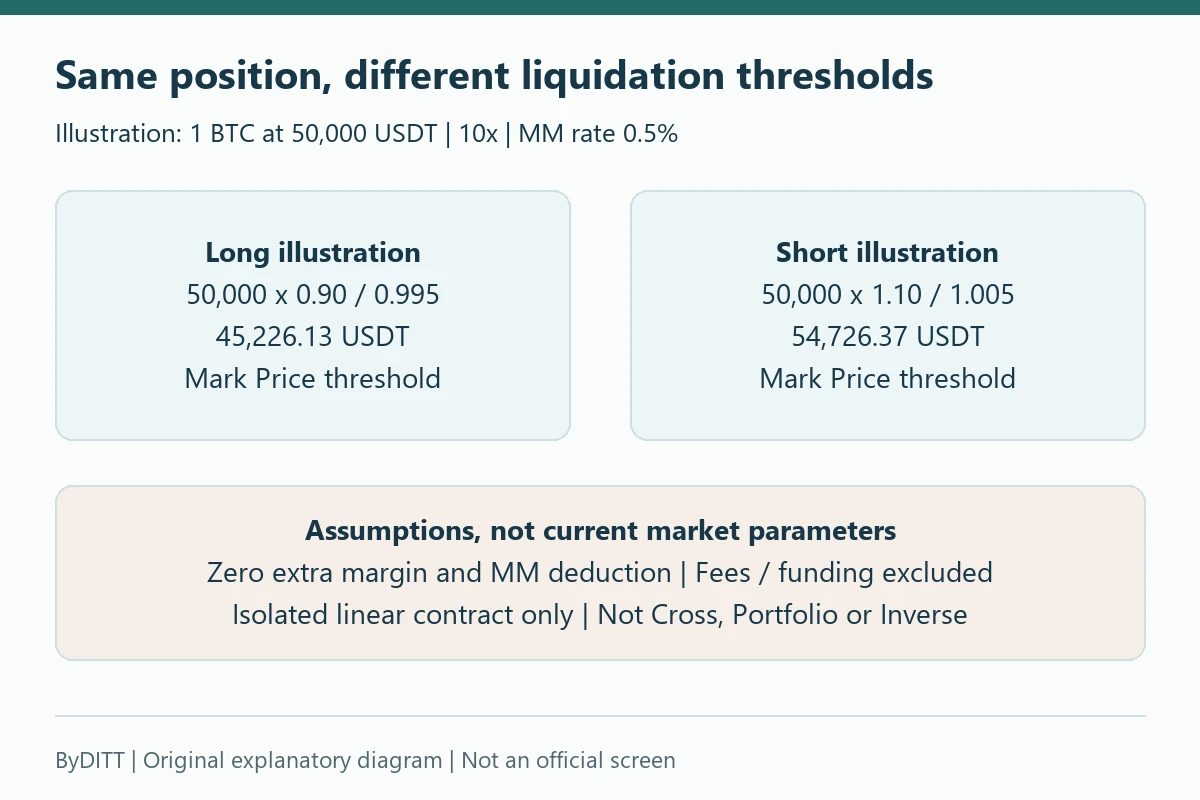
This is not an all-contract formula. Extra margin and maintenance margin deduction change the numerator; other modes and inverse contracts require different treatment. Do not insert account-wide equity into this position-only expression. Before relying on a live number, match the current contract documentation and all its inputs. A small change in assumed rates can matter materially at high leverage.
Cross Margin: account balance supports positions together
In Cross Margin, available account equity can support multiple positions. This can postpone one position’s liquidation, but a losing position can consume collateral that supports the rest of the account. New orders, withdrawals, transfers, collateral-price changes and other positions can change risk.
- Monitor account MMR, not only one displayed liquidation price.
- Check correlations: several “different” positions can lose together.
- Do not withdraw or transfer collateral without recalculating account risk.
- Understand how borrowed assets, interest and collateral value ratios affect equity.
- A reference liquidation price can move as the account changes.
The current UTA liquidation rules: Cross Margin explain that risk reduction can involve order cancellation, repayment and position reductions. A hedge is not a blanket protection of all account assets. Monitor the account indicator rather than waiting for one price line to be touched. A public guide cannot determine the sequence or outcome for your account.
Portfolio Margin: risk is model-based and account-wide
Portfolio Margin can recognize offsets among supported positions, but it requires understanding scenario-based risk. A hedge may not offset as expected when basis, volatility, liquidity, asset correlation or product treatment changes. The absence of a simple fixed liquidation price does not mean liquidation risk is lower.
The UTA liquidation rules: Portfolio Margin state that Portfolio Margin cannot supply a fixed, accurately calculated position liquidation price. No number or a blank price field does not mean there is no risk. The relevant issue is portfolio-level MMR, including changes in offsets, correlations and volatility.
What moves the liquidation threshold
- Entry price and position size
- Leverage and assigned initial margin
- Maintenance margin tier and risk limits
- Added or removed margin
- Trading and estimated closing fees
- Funding payments and receipts over time
- Available account balance and other positions
- Collateral assets, prices and value ratios
- Open orders that reserve margin
- Transfers, withdrawals, borrowing and interest
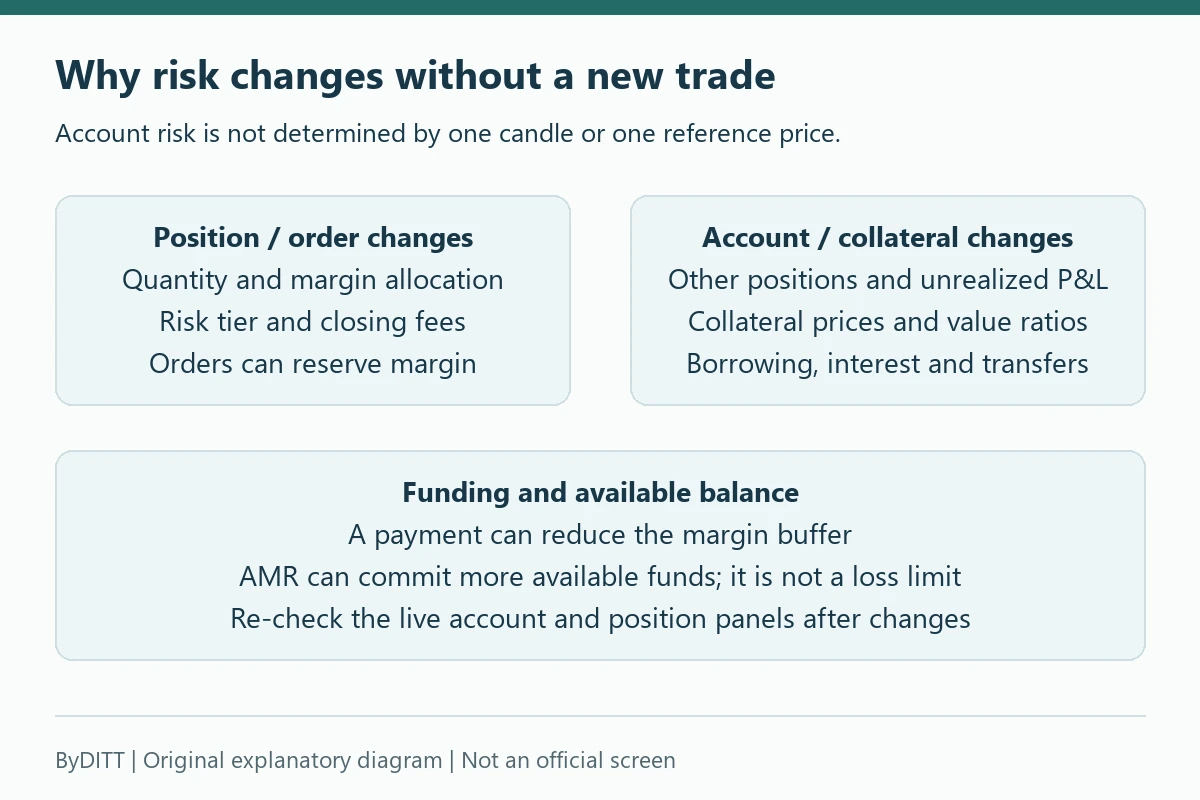
The exact formula depends on contract type, margin mode and current account state. Use the liquidation price and MMR displayed in your own position and account panels. Do not paste an old simplified formula into a calculator and treat it as authoritative.
Why old calculators and the live panel can disagree
The Margin-calculation adjustment and rollout notes describe a rollout beginning 2 September 2025: Mark Price enters maintenance-margin calculations, and risk tiers respond to real-time values. That date is historical, not an upcoming 2026 change. Some paragraphs still describe the old preview stage, so they cannot establish the current rollout status of every account. Use the current product rules and live panel; do not select an old formula just because its answer looks more favorable.
The USDT maintenance margin and tier deduction document a tier deduction: a higher tier is not simply the highest percentage applied without adjustment. The position panel can also include an estimated closing fee. Separately, Risk limits and dynamic tiers explain that position and order exposure can affect tiers, and that selected leverage and a risk-tier adjustment are not the same setting. Copying a percentage from another symbol or an older screenshot is not a valid input check.
- Wrong scope: the calculator assumes one isolated linear contract, but the account uses Cross, Portfolio, an inverse contract or a different settlement asset.
- Stale inputs: position size, added margin, tier deduction, fee assumption or collateral state changed after the screenshot.
- Different fields: position MM rate, account MMR, liquidation price, bankruptcy price and execution price are being compared as if they meant the same thing.
- Incomplete records: a displayed reference is compared with a later candle, but the timestamp, Mark Price or partial fills are missing.
ByDITT’s analysis is that a disagreement is a reason to reconcile scope and inputs, not proof of an exchange error. If the difference remains unexplained, preserve the precise records and ask verified support. Do not increase exposure merely to test a calculator.
Liquidation price is different from bankruptcy price
Liquidation price is the risk threshold where the liquidation engine takes over. Bankruptcy price is the level where the position margin is fully depleted under the relevant model. Bybit’s bankruptcy-price documentation notes that calculations depend on margin mode and that Cross Margin results can be dynamic and only approximate.
The difference between liquidation and bankruptcy prices is relevant to the liquidation process, insurance fund and possible ADL mechanisms. It is not a rebate promised to a liquidated trader. For a detailed explanation, read our bankruptcy price, insurance fund and ADL guide.
Funding and fees can move risk over time
Perpetual positions can pay or receive funding. Trading fees, funding and realized losses reduce equity available to support positions; a funding receipt can increase it. A position that appears safely distant from liquidation at entry can become riskier as costs, collateral and other positions change.
- Check the current funding interval and predicted rate.
- Do not hold solely to collect funding without modelling price and liquidation risk.
- Include opening, closing and potential taker fees in the loss budget.
- Monitor longer-held positions after each funding settlement.
See our Bybit funding fee guide for rate, settlement and payer mechanics.
The Funding fee calculation and deduction say that if available balance is insufficient, funding can be taken from position initial margin and move the Isolated Margin threshold closer. Check the actual settlement record, not only the predicted rate. Auto-Margin Replenishment can commit additional available funds in supported Isolated products; it changes effective leverage, not a guaranteed maximum loss. Do not assume unused account funds remain untouched when that feature is enabled.
Practical controls that reduce liquidation risk
- Define the maximum account loss before calculating position size.
- Use materially lower leverage than the maximum available.
- Select Isolated, Cross or Portfolio Margin deliberately.
- Place the stop with the intended trigger type and sufficient buffer.
- Set alerts for Mark Price, MMR, equity and available margin.
- Reduce correlated positions and open orders that consume margin.
- Recalculate after funding, transfers, withdrawals or collateral changes.
- Close or reduce exposure before the account depends on emergency execution.
No universal rule such as “5% per position” or “3× to 10× is professional” fits every asset, volatility regime or account. Use a loss budget and scenario analysis instead of labels.
How to review a liquidation after it happens
The Order execution, stop triggers and liquidation history documents the record route. On the website, open Orders, Unified Trading Order, Futures, then Trade History and filter Filled Type to Liquidation. In the app, use the trading-page history icon and the same Trade History filter. Interface labels may vary by version and entity. These are instructions to inspect records, not actions ByDITT can perform inside your account.
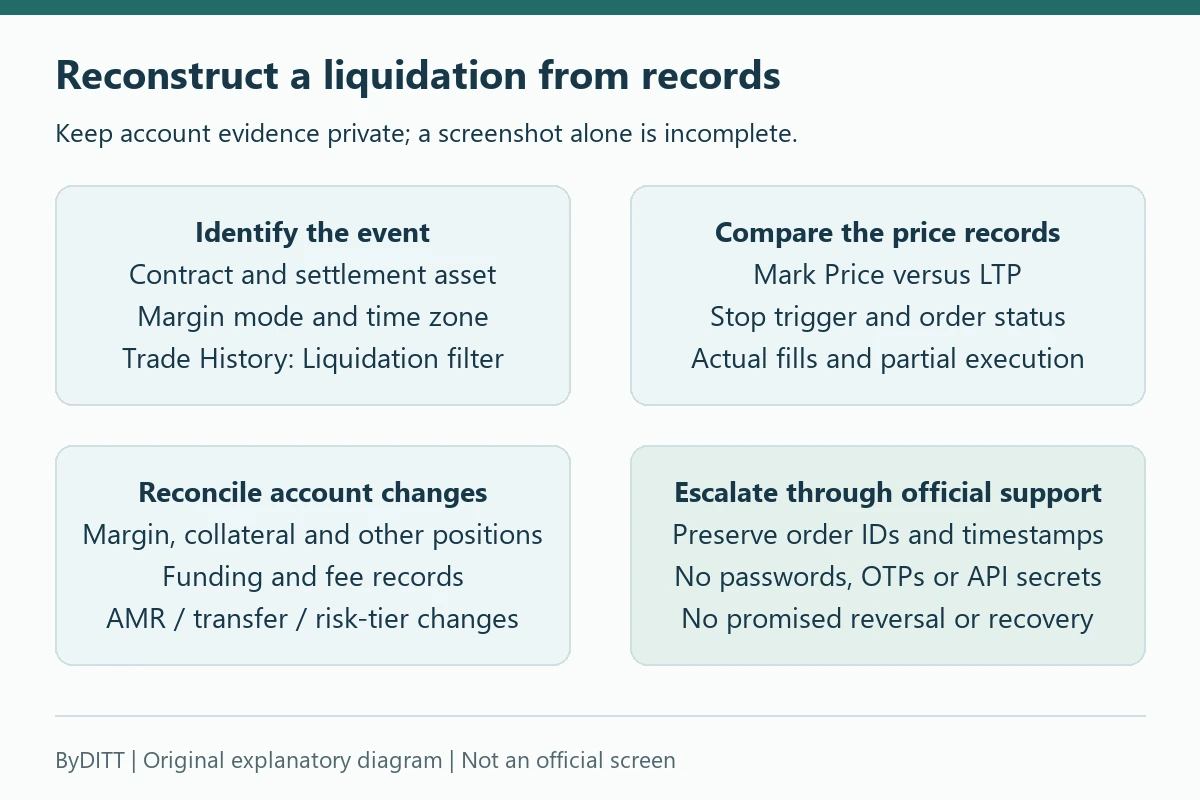
- Record the contract, settlement asset, position side, margin mode, event time and time zone. Keep order or trade references privately.
- Compare the Mark Price record with LTP at the relevant time. A chart screenshot of a different price series is incomplete evidence.
- Inspect stop trigger type, order type, active or rejected status, quantity and actual fills. Distinguish a liquidation record from an ordinary manual or stop exit.
- Reconcile margin additions or removals, AMR, funding, fees, transfers, other positions and collateral changes around the event.
- If a discrepancy remains, use independently opened official support. Share necessary case evidence through that secure channel, not public comments. Never provide passwords, OTPs, recovery phrases or API secrets.
A historical record can help explain what occurred, but a public article cannot reconstruct a complete risk engine state, certify an account fault or promise compensation. Liquidation, normal stop execution and ADL are different events. For the bankruptcy-price, insurance-fund and ADL boundary, use the dedicated guide linked above instead of assuming every forced reduction is the same mechanism.
Pre-trade liquidation checklist
- I know the contract and settlement asset.
- I know which margin mode applies.
- I checked Mark Price and the displayed liquidation risk.
- I understand whether account MMR or position price is the trigger.
- I calculated combined exposure across open positions.
- My stop trigger type and size match my plan.
- I included fees, funding and slippage.
- I can tolerate the loss without adding emergency margin.
Affiliate disclosure: ByDITT is an independent educational and affiliate site, separate from Bybit.com, and may receive compensation if you use this optional registration link. BYBITDC is an affiliate code, not a margin-control feature or support credential. It does not guarantee a discount, change eligibility, reduce leverage, prevent liquidation or guarantee a stop fill. The link is not required to inspect liquidation records.
Educational information only, not financial advice. Derivatives can cause rapid and total loss of allocated capital. Product formulas, risk limits and liquidation rules can change; verify the live Bybit Help Center and your account.
Official sources and verification date
Checked on 19 October 2026. Displayed document update dates are listed where available; they are not a claim that every account received a change on that date. The Isolated, Cross and Portfolio links open the corresponding official rule tabs. Verify your product entity, eligibility and account notices before interpreting a calculation.
- UTA liquidation rules: Isolated Margin — updated 2026-10-15
- UTA liquidation rules: Cross Margin — updated 2026-10-15
- UTA liquidation rules: Portfolio Margin — updated 2026-10-15
- Order execution, stop triggers and liquidation history — updated 2026-09-25
- Margin-calculation adjustment and rollout notes — updated 2026-06-18
- USDT maintenance margin and tier deduction — updated 2026-04-16
- Risk limits and dynamic tiers — updated 2026-09-04
- Mark Price calculation — checked 2026-10-19
- Bankruptcy Price — checked 2026-10-19
- Funding fee calculation and deduction — updated 2026-05-12
- Auto-Margin Replenishment — updated 2026-03-25